
Quicken: Intelligent Money
Quicken Inc.Finance
- Rating
- 4.7
- 1.4K Reviews
- Downloads
- 500K+
- Age Rating
- Everyone
App Specs
- Version
- VARY
- Updated
- Requires
- VARY
- Price
- Free
Screenshots
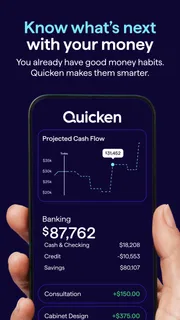
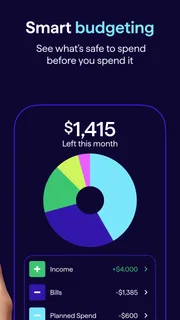
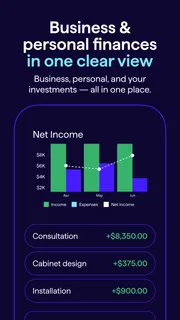
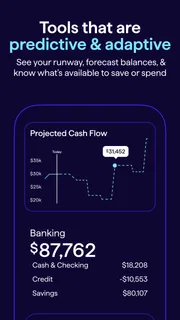
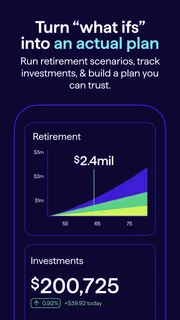
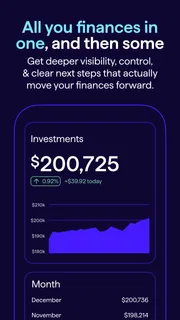
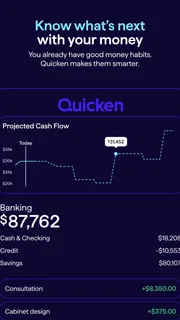
Our Review
 Analysis byMileapps
The first few days with Quicken Simplifi can feel satisfying for a simple reason: scattered accounts and spending details start to look like one manageable picture. I like this kind of finance app most when it helps me notice what needs attention without turning every purchase into a chore. That balance is the real test, though. A budget tool earns a lasting place on my phone through steady usefulness, not just the novelty of a colorful dashboard.
What the first week can clarify
As a personal finance app from Quicken Inc., Quicken Simplifi is aimed at people who want a broad view of their money rather than a strict, envelope-by-envelope routine. Its appeal is easy to understand: bring accounts together, review spending, and use a spending plan to make upcoming choices with more context. The app is free to download, with in-app purchases listed from $8.99 to $95.90 per item, so I would check the current purchase details before deciding whether its paid options suit my needs.
Getting an overview is only useful if the information looks believable. During the first week, I would compare a few transactions against the bank or card accounts they came from, check how the app assigned categories, and correct anything that does not fit. That small review is more valuable than immediately trying to perfect every budget target. If the starting categories are off, the reports can look precise while telling the wrong story.
A practical first-week test is to set a spending plan around a real upcoming expense rather than an abstract goal. For example, if I know groceries and a recurring bill are due before payday, I can see whether the plan makes that timing visible and whether its reminders help me act. If the app makes the next decision clearer, it has already done more than display old transactions.
Where it can earn a monthly routine
The spending plan is the feature I would return to most often. Instead of checking every purchase in isolation, I can use it to ask a more useful question: after the bills and expected costs, how much room is left for flexible spending? That is especially helpful when income arrives on a regular schedule but expenses do not. A plan is not a promise that every month will behave; it is a way to notice when the month is drifting early enough to adjust.
Alerts can support that habit, but I would choose them carefully. Upcoming-bill and balance notifications are most useful when they prompt a specific action, such as checking an account before a payment or moving a planned purchase to another week. If every small change generates noise, I am more likely to ignore the messages that matter. The best setup is the lightest one that still catches the events I personally tend to miss.
Reports become more revealing once there is enough history to compare. I would use them to investigate one question at a time: did dining out rise, are irregular household costs clustering in the same month, or is a category too broad to guide a decision? A month-to-month check is often more actionable than staring at a long-range chart. The goal is not to judge every purchase after the fact; it is to use a pattern to make the next month less surprising.
The upkeep that a dashboard still needs
Automatic categorization can save effort, but it does not remove the need for occasional housekeeping. A retailer may be assigned to a category that is technically plausible but not useful for my budget, and one mistaken label can distort a trend. I would set aside a brief, regular review to correct unusual transactions and keep categories consistent. Making a few deliberate corrections is usually better than building a complicated category system that becomes a second job.
That same approach helps when spending changes. A one-off trip, a gift, or an annual charge can make a normal month look unusually expensive. Rather than treating every spike as a new habit, I would separate unusual costs mentally and look at recurring patterns across several periods. The useful question is whether I should change a plan going forward, not whether a chart can make a past month look tidy.
It is also worth considering how comfortable I am with connecting financial accounts to an app. The original article describes encryption and multi-factor authentication, but I would still review the security options available to me and use a strong, unique sign-in. Convenience and account visibility come with a need to make sensible security choices. Anyone who prefers not to link accounts may find manual tracking or a simple spreadsheet more comfortable, even if it takes more effort.
Who benefits—and who may tire of it
This setup is a strong fit for someone who has several accounts, wants a consolidated view, and is willing to spend a little time checking that transactions are categorized sensibly. It may also suit a household trying to discuss spending from a shared picture, provided everyone agrees on how to interpret the plan. Someone who mainly wants a quick glance at balances may find the broader budgeting tools more than they need, while a person who enjoys recording every purchase by hand may prefer a more deliberately manual method.
Compared with a basic bank app, a dedicated finance tool can be more useful for looking across accounts and thinking about spending as a whole. Compared with a spreadsheet, it can reduce routine entry and offer a more immediate overview, though a spreadsheet gives its owner more control over structure and assumptions. Strict cash-envelope budgeting is a different philosophy: it can make limits feel more concrete, while a flexible spending plan may feel easier to maintain for someone who wants guidance without assigning every dollar a rigid job.
The small-business tools mentioned for the app may interest people who want personal finance and some business-related visibility in the same general toolkit. I would not assume that this makes it a replacement for dedicated bookkeeping or tax software. If invoices, detailed expense records, or formal accounting workflows are central to the job, a specialist product is a safer comparison. The right choice depends on whether the app’s broader overview is enough or whether the work requires purpose-built records.
When convenience turns into fatigue
The main risk is not that a budget plan fails; it is that I stop looking at it. An alert-heavy setup, too many custom categories, or repeated corrections can make a helpful routine feel like admin. I would start with a few categories that answer real questions, then add detail only when a recurring blind spot appears. If I cannot explain what a category helps me decide, it probably does not need to be there.
Another source of fatigue is expecting the app to make decisions on my behalf. A report can show that a cost is rising, but it cannot tell me whether that cost matters more than another priority. Nor does a spending plan prevent an unexpected bill. I find these tools most useful as a prompt for a short check-in, not as a verdict on whether I have been “good” with money.
People comparing finance apps should also ask what kind of control they value. Those who want a highly customized, hands-on ledger may be happier with a spreadsheet or a more manual tracker. Those who want a strict debt-payoff method or specialist business accounting should compare products built around those jobs. Simplifi is most compelling when the everyday task is seeing the wider picture and keeping an adaptable plan in view.
Does it deserve a place after the novelty?
Quicken Simplifi has an average rating of 4.3 from around 4,200 ratings, and it has been installed more than 500,000 times. It is rated for Everyone and was released on October 1, 2019. Those figures offer context, but my decision would come down to whether I keep using its plan and reports after the first burst of setup is over. I would give it a fair trial through an ordinary month, including at least one bill cycle, before deciding whether the routine feels worthwhile.
For everyday budgeting, I would recommend it to someone who wants a connected view and is comfortable doing light maintenance. I would skip it if linking accounts feels like an unacceptable trade-off, if I only need a balance check, or if I need detailed bookkeeping rather than general business-related tools. In those cases, a bank’s own app, a spreadsheet, or specialist software may fit better.
What I like most is the possibility of turning scattered financial details into a short, repeatable check-in: review what changed, correct what is misleading, and decide what deserves attention next. That is a modest promise, but it is the kind that can last. If the app helps me make that habit easier without demanding constant tuning, it has earned its space; if I find myself managing the dashboard more than my money, I would move on.
Ever feel like your finances are a jigsaw puzzle and you're missing a few crucial pieces? Well, that's where Quicken Simplifi swoops in like a superhero in a budgeting cape. This app is all about making your financial life a whole lot simpler, and trust me, it lives up to the name.
Getting Started with Quicken Simplifi
First things first, setting up Quicken Simplifi is a breeze. Once you download the app — available on both Android and iOS, by the way — you'll be greeted by a clean and intuitive interface that practically begs you to start organizing your finances. You can sync your bank accounts, credit cards, and even investment accounts in just a few taps. It's like magic, but with numbers.
The app does a fantastic job of categorizing your expenses automatically, saving you from the drudgery of manual entry. If you're like me and can't remember whether that coffee run was on Tuesday or Wednesday, you'll appreciate the app's accuracy. Plus, you can always tweak categories or add new ones to suit your unique spending habits.
Features That Make Life Easier
Quicken Simplifi isn't just about tracking expenses — it's about giving you a complete picture of your financial health. One of my favorite features is the spending plan. It's like having a financial advisor in your pocket, nudging you to stay on track without being too pushy. You set your financial goals, and the app helps you stick to them by gently reminding you of your limits. It's almost like having a personal trainer for your wallet.
Then there’s the customizable alerts. You can set notifications for upcoming bills, low balances, or even when you’ve been a little too swipe-happy with the credit card. It’s like having a financial buddy keeping an eye on things for you.
Insights and Reports
If you're a data geek like me, you'll love the insights and reports feature. The app breaks down your spending habits over weeks, months, or even a year. It’s fascinating (and sometimes terrifying) to see where your money actually goes. This kind of data can be a real eye-opener, helping you adjust your spending habits for the better.
What I really appreciate is how visually appealing the reports are. Colorful graphs and charts make it easy to digest information at a glance. You won't have to wade through boring spreadsheets here, my friend.
User Experience and Interface
Now, let's talk about the app's vibe. The user experience is smooth — buttery smooth, even. Navigating through the app feels intuitive, and everything is exactly where you expect it to be. The design is modern without being flashy, and it feels like the developers really thought about what users need at each step.
Plus, there’s a community aspect if you want it. You can connect with other users to share tips or ask questions. It’s like having a support group that actually understands your financial woes.
Security and Peace of Mind
In this digital age, security is a big deal, and Quicken Simplifi doesn’t take it lightly. The app uses bank-level encryption to ensure your data is safe and sound. Plus, it offers multi-factor authentication for that extra layer of security. It’s like having a digital vault for your sensitive information.
Knowing that your financial data is secure allows you to focus on what really matters: managing your money effectively without any added stress.
In conclusion, if you're looking for an easy-to-use, reliable, and feature-rich app to manage your finances, Quicken Simplifi is absolutely worth a shot. It's not just about budgeting; it's about empowering you to make smarter financial decisions. So go ahead, give it a whirl, and watch as your financial puzzle pieces start to fit together perfectly.
Pros and Cons
Pros
- User-friendly interface simplifies budgeting.
- Real-time syncing across multiple devices.
- Customizable spending categories.
- Insightful financial reports and alerts.
- Secure data encryption for safety.
Cons
- Subscription required for full features.
- Limited offline functionality.
- No support for cryptocurrency tracking.
- Occasional syncing issues reported.
- Initial setup can be time-consuming.
Frequently Asked Questions
What platforms is Quicken Simplifi available on?
Quicken Simplifi is available for both Android and iOS platforms, making it accessible for a wide range of smartphone users. You can download it from the Google Play Store for Android devices or the Apple App Store for iOS devices. This ensures that users can manage their finances on the go, regardless of their preferred operating system.
Does Quicken Simplifi offer real-time financial updates?
Yes, Quicken Simplifi provides real-time financial updates. It automatically syncs with your bank accounts, credit cards, and other financial institutions to give you up-to-date information on your transactions and balances. This feature helps you to keep track of your spending and savings efficiently, allowing for better financial management.
Is there a subscription fee for using Quicken Simplifi?
Quicken Simplifi operates on a subscription model. While the app offers a free trial period to explore its features, continued use requires a monthly or annual subscription. The subscription fee ensures you have access to its full range of features, including budget tracking, spending categorization, and personalized financial insights.
How secure is my financial data with Quicken Simplifi?
Quicken Simplifi prioritizes the security of your financial data. It uses bank-level encryption and multi-factor authentication to protect your information. Additionally, it does not store your bank credentials, further safeguarding your privacy. These measures ensure that your data remains secure while you manage your finances through the app.
Can I customize budget categories in Quicken Simplifi?
Yes, Quicken Simplifi allows you to customize budget categories to better fit your personal financial needs. You can create, modify, and personalize categories, ensuring that your budget aligns with your unique spending habits and financial goals. This flexibility helps users manage their finances in a way that suits their lifestyle.

Download Quicken: Intelligent Money
Close Matches in This Category
 Google WalletFinance4.4
 Airtel: Recharge, Bank & LoansFinance4.0
 DANA Indonesia Digital WalletFinance4.5
 Binance: Buy Bitcoin & CryptoFinance4.8
 Inter Banking & Money TransferFinance4.4
 Cash AppFinance4.7
 PayPal - Pay, Send, SaveFinance4.2
 MetaTrader 5 — Forex, StocksFinance4.7